Renewing health insurance plans without reviewing the details can leave you paying more for coverage that no longer fits. A familiar plan name does not guarantee the same premium, doctor network, prescription coverage or deductible next year. Before accepting automatic renewal, compare what is changing with the care your household expects to need.
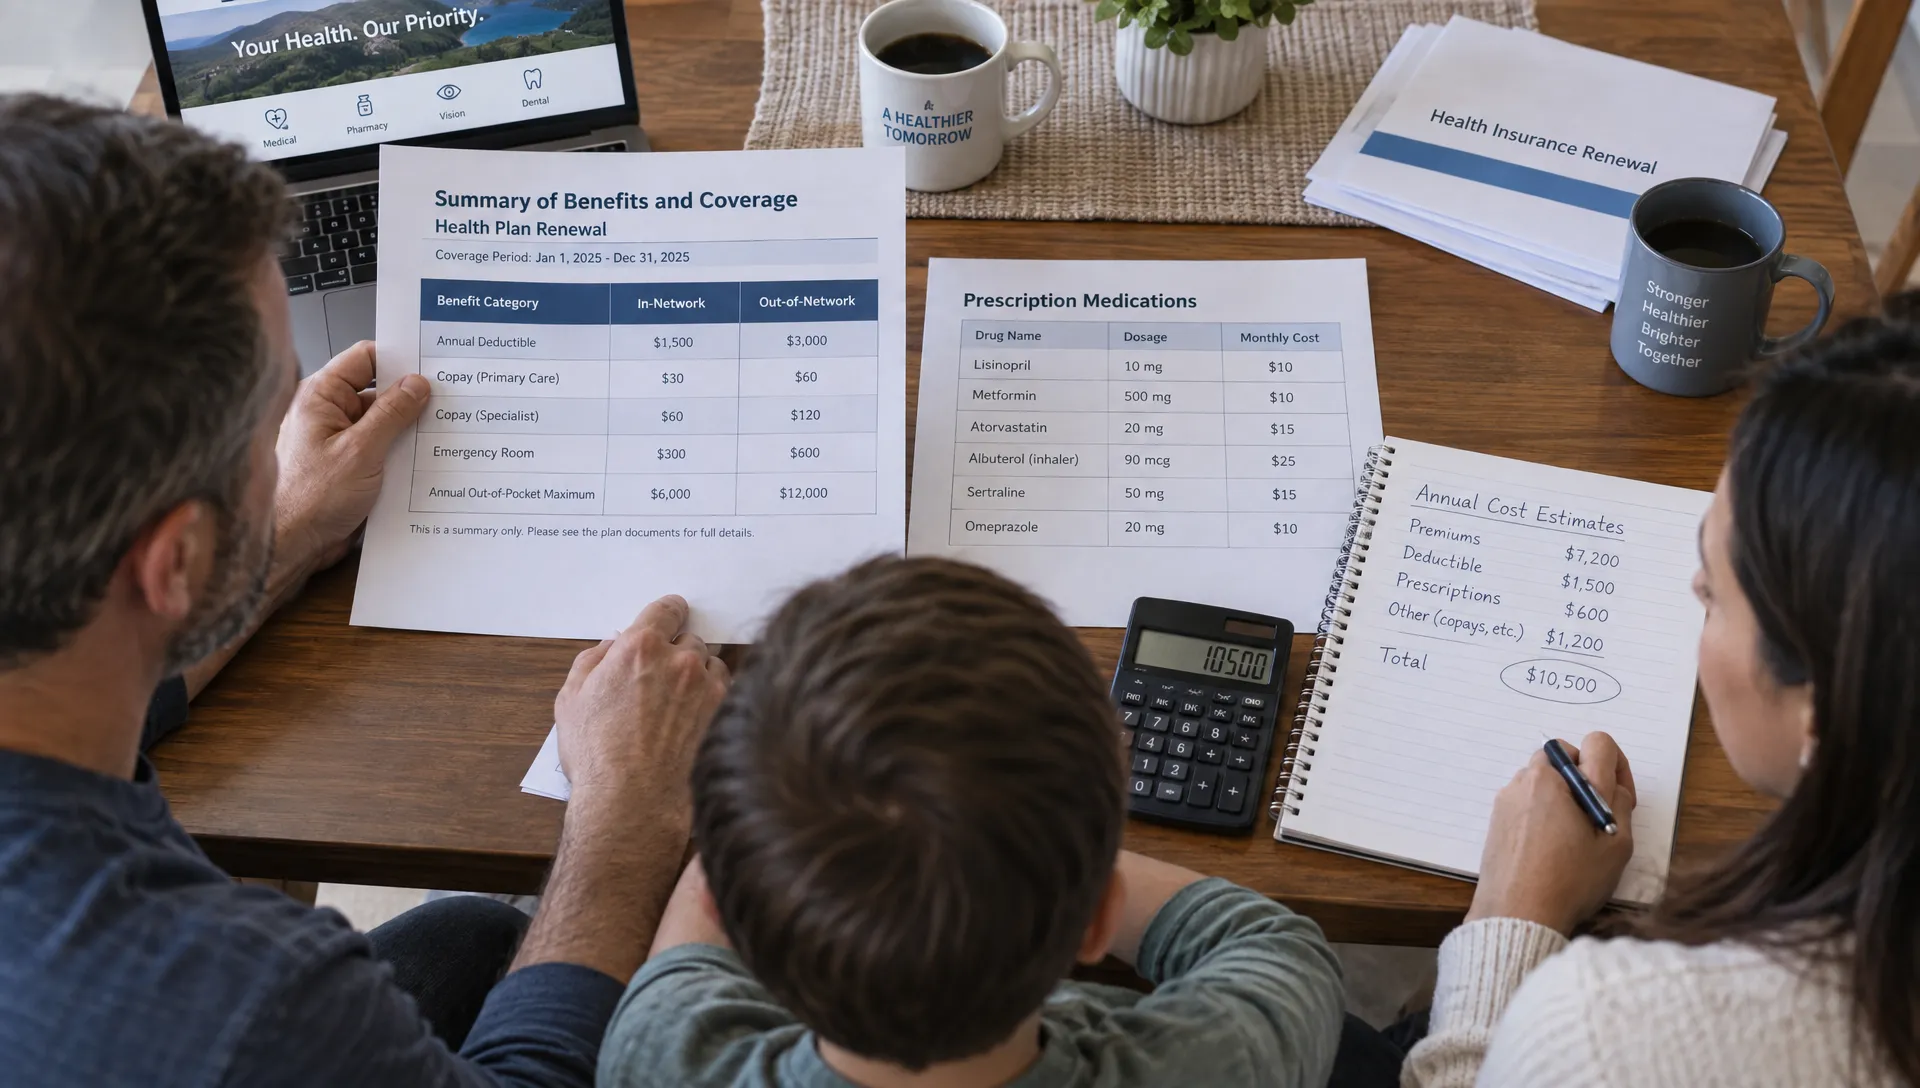
Start with your renewal notice, the upcoming year’s Summary of Benefits and Coverage (SBC), the provider directory and the prescription drug formulary. Keep recent medical bills and a list of medications nearby. Those documents make it easier to spot changes that affect your actual spending, rather than choosing on monthly premium alone.
This checklist focuses on individual, family and employer-sponsored coverage. Medicare has separate enrollment rules and notices. For any coverage, use documents for the upcoming plan year, not the benefits you have today.
1. Compare total yearly costs, not just premiums
Your premium is only one part of your budget. A cheaper monthly payment can come with a higher deductible, larger specialist copays or more expensive prescriptions. Review both your expected spending and your exposure in a year with substantial medical needs.
A practical estimate is:
Estimated annual cost = 12 months of premiums + expected out-of-pocket spending for care.
For employer coverage, use your actual payroll deductions and the number of deductions each year. For Marketplace coverage, use the premium after any confirmed financial assistance.
The following example uses hypothetical figures, not actual quotes:
| Cost item | Plan A | Plan B |
|---|---|---|
| Monthly premium you pay | $300 | $340 |
| Annual premiums | $3,600 | $4,080 |
| Estimated out-of-pocket spending | $1,800 | $800 |
| Estimated annual total | $5,400 | $4,880 |
Although Plan B costs more each month, it costs less under these assumptions. Your own estimate should reflect planned appointments, recurring prescriptions and any scheduled procedures.
When comparing health insurance plans, also examine the individual and family deductibles, separate prescription deductibles and out-of-pocket maximums. The maximum generally applies to covered, in-network care, not premiums, uncovered services or all out-of-network expenses. HealthCare.gov explains these exclusions.
If you have family coverage, check how individual and family thresholds work together. Do not assume one family member must meet the entire family deductible before benefits begin.
2. Verify your doctors, hospitals and other providers
A carrier’s name is not enough to confirm access to your current doctors. The same insurer may offer several networks, and a provider who participates in one may not participate in another.
Search the upcoming year’s directory using the exact plan and network name. Check your primary care clinician, specialists, preferred hospital and any recurring services, such as a laboratory, imaging center or physical therapy practice.
Then confirm participation with the insurer and the provider’s billing office. Ask, “Will this clinician at this location be in-network for this exact plan during the upcoming plan year?” A general answer that the office “takes” the insurer is not sufficient.
Provider access can make otherwise similar health insurance plans very different in practice. A lower premium may be poor value if you must change an established specialist or travel much farther for treatment.
Also review referral requirements and whether nonemergency out-of-network care is covered. If a provider is leaving the network during ongoing treatment, ask about continuity-of-care protections and the process for requesting them. Availability depends on the circumstances and applicable rules, so obtain confirmation rather than assuming an exception applies.
Keep dated notes or written responses, particularly when preserving access to an existing care team is a priority.
3. Recheck every prescription and its restrictions
Do not assume a medication will keep the same coverage simply because it was covered this year. Formularies can change, along with drug tiers, pharmacy networks and approval requirements.
Look up each medication by its exact name, strength and formulation. Compare the prescribed brand or generic version, rather than relying on a broad drug category.
For medications you take regularly, check these details:
- Coverage and tier: Whether the drug is covered and which cost-sharing tier applies.
- Your payment: Whether you owe a copay, coinsurance or the full negotiated cost before meeting a deductible.
- Restrictions: Prior authorization, step therapy or quantity limits.
- Dispensing rules: Preferred pharmacies, specialty pharmacies and availability of extended supplies.
HealthCare.gov’s prescription coverage guidance explains how to check covered drugs and what to do when a medication is not covered.
Prescription differences between health insurance plans can outweigh modest premium savings, especially with recurring specialty medications. Request an estimate for your specific prescriptions under each finalist, recognizing that percentage-based coinsurance may vary with the drug’s negotiated price.
If you switch coverage, ask whether an existing authorization remains valid or whether your clinician must submit a new request. Discuss any refill timing with your prescriber and pharmacist before the change takes effect.
4. Read the benefit changes and coverage limitations
Your renewal notice deserves a line-by-line review. Compare the upcoming SBC with the current version, then consult the full policy or plan documents when a detail is unclear. The SBC is a useful summary, but it does not contain every coverage condition.
Pay particular attention to services you used this year or expect to use next year. Changes to outpatient surgery, emergency care, mental health visits, rehabilitation or diagnostic imaging may matter more to your household than a benefit you rarely use.
Check whether a service has moved from a fixed copay to coinsurance. Also review visit limits, exclusions, referral rules and prior authorization requirements. Coverage for a service does not necessarily mean every provider, setting or treatment approach qualifies.
If the terminology is unfamiliar, Insurance 2ALL’s guide to understanding your health coverage can help you interpret the documents before comparing changes.
The most useful review of health insurance plans connects those terms to a specific situation. If you expect knee surgery, for example, ask about the surgeon, facility, anesthesia, imaging and follow-up therapy instead of checking only whether “surgery” is covered.
For ongoing treatment, verify whether approvals, referrals or treatment limits reset with the new coverage period. Obtain answers in writing when possible and save any reference numbers.
5. Recalculate financial assistance and employer contributions
Last year’s premium is not a reliable estimate for next year, even when the plan itself remains available. Changes in financial assistance or an employer’s contribution can alter what you pay.
For Marketplace coverage, review your projected household income for the coverage year, tax household, address and access to other coverage. Follow the application’s instructions rather than simply copying last year’s answers. Update information that has changed and provide requested documentation.
Use the Marketplace’s current eligibility result to compare health insurance plans, not an assumption that your previous subsidy will continue unchanged. Advance premium tax credits are reconciled on your federal tax return, so an inaccurate income estimate can affect that reconciliation.
Also check whether you qualify for cost-sharing reductions. These can lower deductibles, copays and other out-of-pocket costs, but generally require enrollment in a Silver Marketplace plan. HealthCare.gov explains how this assistance works.
For employer coverage, compare the upcoming employee contribution for each coverage tier. Employee-only, employee-plus-spouse and family coverage may change by different amounts. Check any applicable spouse surcharge and whether employer contributions to a health savings or reimbursement account are changing.
Finally, make sure every quote uses comparable assumptions. A subsidized Marketplace premium and an unsubsidized quote are not directly comparable unless you know which amount applies to your household.
6. Match coverage to next year’s household needs
Renewal should reflect the year ahead, not just the year that ended. Consider changes in employment, residence, dependents and expected medical care before deciding to keep your current coverage.
A move may affect available networks and service areas. A dependent approaching age 26 may need separate coverage, with the exact termination date depending on the plan. A change in either spouse’s job may introduce another employer option or change eligibility for Marketplace assistance.
Compare the options available to the household rather than assuming everyone must stay on one policy. Sometimes separate coverage makes sense, but compare total premiums, separate deductibles and provider access before deciding.
The right health insurance plans for your household should also accommodate practical needs. Someone who travels regularly, studies away from home or receives specialized treatment may need to check access beyond the nearest primary care office.
If you anticipate a job transition, review your coverage end date and replacement options early. Insurance 2ALL’s guide to maintaining health insurance between jobs addresses that situation in more detail.
For planned treatment spanning two coverage periods, ask how a deductible reset or insurer change could affect costs and approvals. Meeting this year’s deductible does not usually mean you have satisfied next year’s deductible. Check your plan’s benefit-year dates, especially if they differ from the calendar year.
7. Confirm deadlines and enrollment for health insurance plans
Automatic renewal is convenient, but it is not a substitute for reviewing your enrollment. Your insurer may change the plan or discontinue it, and an automatic replacement may not preserve the benefits or network you want.
Confirm your renewal status, available alternatives, selection deadline and effective date. Check the official Marketplace for your state or your employer’s benefits portal for the upcoming coverage year. Enrollment dates and procedures can differ by coverage source, so do not rely on last year’s calendar or assume Medicare dates apply.
Before the deadline, complete a short final check:
- Selected coverage: Verify the exact plan, covered household members and effective date.
- Required steps: Submit any requested eligibility documents and complete the enrollment process.
- Payment arrangements: Confirm any required first payment, updated premium and automatic payment instructions.
- Proof of enrollment: Save the confirmation, benefit documents and insurer contact details.
If you are changing insurers, coordinate the old plan’s end date with the new plan’s confirmed start date. Do not cancel existing coverage before confirming when replacement coverage begins.
Enrollment outside the regular window may require a qualifying event or another eligibility pathway. Missing the deadline can therefore leave you with fewer options, not merely delay the decision.
Once enrolled, check that your account reflects the correct coverage and household members. Resolve discrepancies before you need an appointment or prescription refill.
Frequently Asked Questions
Should I renew automatically if I liked my coverage this year? Only after checking next year’s costs, network, medications and benefits. A satisfactory experience this year does not guarantee unchanged coverage. Automatic renewal may be reasonable when those details still meet your needs.
Can I change plans if my premium increases? You can generally choose another available plan during the applicable open enrollment period. Outside that period, switching usually depends on a Special Enrollment Period or another eligibility pathway. A premium increase alone does not necessarily let you switch at any time.
Does my deductible carry over when coverage renews? Deductibles typically reset at the start of the plan’s benefit year. If you change plans, do not assume amounts already paid will transfer. Ask whether any deductible credit applies and obtain confirmation of the rules.
How many health insurance plans should I compare before renewing? There is no required number. Compare your renewal offer with a few realistic alternatives using the same household information, providers and medications. A focused comparison is more useful than reviewing many plans that cannot meet your needs.
Get help comparing your renewal options
Have your renewal notice, provider list and prescriptions ready when requesting quotes. Insurance 2ALL offers free, no-commitment insurance comparisons across 50+ carriers, with licensed advisor guidance, bilingual support and enrollment application assistance. Available options depend on your location and circumstances. Ask for help comparing your current renewal offer with alternatives based on total costs and the care you need.