Choosing Medicare Original vs. Medicare Advantage matters differently when you spend months away from home, visit family across state lines or travel overseas. A plan that works well cerca de ustedr primary residence may handle routine appointments, prescription refills and emergencies very differently once you leave its service area.
For frequent domestic travelers, Medicare Original generally offers broader provider access, especially when paired with suitable supplemental . Medicare Advantage can still fit travelers whose plans cover care where they actually spend time. For international trips, neither option should be assumed to provide comprehensive protection.
Medicare Original vs. Medicare Advantage: Travel Cobertura at a Glance
Medicare Original consists of Part A and Part B. Medicare Advantage, also called Part C, is a private-plan alternative that provides your Part A and Part B benefits, usually with prescription drug coverage included.
The travel question is not simply whether you have . It is which care is covered, where you can receive it and what you will owe.
| Travel consideration | Medicare Original | Medicare Advantage |
|---|---|---|
| Routine care within the U.S. | Access to providers nationwide that accept Medicare | Depends on the plan’s network and out-of-network benefits |
| U.S. emergencies and urgently needed care | Covered when Medicare requirements are met | Covered outside the service area, including outside the network |
| Consultas con especialistas while away | Generally no referral required | Referral and authorization rules depend on the plan |
| Foreign medical care | Usually not covered, with limited exceptions | Extra overseas benefits may be available, depending on the plan |
| Supplemental protection | Medigap can help with covered cost-sharing; certain policies include foreign emergency benefits | Medigap cannot pay Medicare Advantage cost-sharing |
| Annual medical spending limit | No annual limit on Part A and Part B out-of-pocket costs without supplemental protection | Annual limit for covered Part A and Part B services, subject to network rules |
Medicare’s official comparison of Medicare Original and Medicare Advantage explains the underlying coverage differences. For travelers, provider access often deserves more attention than extras such as fitness memberships or routine dental benefits.
Traveling Within the U.S.: Separate Routine Care From Emergencies
Routine appointments and ongoing treatment
With Medicare Original, you can generally receive Medicare-covered care from providers that accept Medicare throughout the country. There is no local plan network. Sin embargo, a practice may not accept new patients, and accepting Medicare does not always mean accepting Medicare’s approved amount as full payment.
Medicare Advantage works differently. An HMO generally requires dentro de la red providers for routine care, with limited exceptions. A PPO typically permits covered out-of-network care, usually at higher cost. An out-of-network provider must also agree to treat you and bill the plan; accepting Medicare Original does not automatically mean accepting your Advantage plan.
When comparing Medicare Original vs. Medicare Advantage, map out predictable treatment first: physical therapy, specialist follow-ups, infusions, imaging and chronic-condition monitoring. These services are not automatically covered outside an HMO network just because you are traveling.
A plan may also require prior authorization for a service even when the treating provider is dentro de la red. Nuestra guía sobre Medicare Advantage referral requirements explains why a specialist referral and approval for a procedure are separate issues.
Emergencies, urgently needed care and dialysis
planes Medicare Advantage must cover emergency care and urgently needed services outside their service area. They must also cover qualifying out-of-area dialysis. These protections are different from permission to schedule any routine appointment wherever you happen to be.
Por ejemplo, treatment for an unexpected illness that cannot reasonably wait until you return home may qualify as urgently needed care. A planned annual examination generally would not qualify on that basis alone.
In a medical emergency, seek care immediately rather than delaying to check a directory. Once you are stable, contact the plan about follow-up treatment, discharge arrangements and any proposed transfer. Continued care after stabilization can involve different coverage rules.
If you receive dialysis, arrange a destination facility before departure and confirm how it will bill your .
Snowbirds, RV travelers and extended stays
Someone spending four months each winter en another state needs more than emergency protection. Check whether the plan covers routine care at the second location, including specialists and diagnostic facilities.
A national insurance company does not necessarily provide a nationwide network for every plan it sells. Some planes Medicare Advantage offer visitor or travel benefits, but eligibility, locations and permitted services vary.
For snowbirds weighing Medicare Original vs. Medicare Advantage, the length of each absence matters too. planes Medicare Advantage generally must disenroll members who remain outside the service area for more than six months, although some plans have qualifying extended-travel arrangements that allow longer absences, sometimes up to 12 months. Confirm the applicable rules directly with the plan.
A permanent move is different from a vacation and can create a Período Especial de Inscripción. Full-time RV travelers should verify that their actual residence meets the plan’s service-area requirements rather than assuming a mailing address alone is sufficient.
International Travel: Neither Option Is Comprehensive Travel Seguros
Medicare Original’s foreign-coverage exceptions
Medicare Original generally does not cover health care outside the United States. For Medicare purposes, U.S. coverage includes Puerto Rico, the U.S. Virgin Islands, Guam, American Samoa and the Northern Mariana Islands.
There are narrow foreign-hospital exceptions. They include certain emergencies when a foreign hospital is closer than an appropriate U.S. hospital, qualifying emergencies during direct travel through Canada between Alaska and another state and certain situations where a foreign hospital is closer to a U.S. resident’s home.
Medicare’s rules for travel outside the U.S. explain these exceptions. They are not a reliable substitute for overseas medical insurance.
For international travelers comparing Medicare Original vs. Medicare Advantage, the practical next step is to examine any additional foreign emergency benefits separately. An Advantage plan may offer them, but the benefit can have its own deducible, reimbursement process and payment limits.
What Medigap can and cannot add
Certain Medigap policies, including standardized Plans G and N, provide a foreign travel emergency benefit. Under the standardized benefit, the policy generally pays 80% of eligible charges after a $250 calendar-year deducible when the emergency begins during the first 60 days of the trip. A $50,000 lifetime limit applies.
These limits make the benefit useful but incomplete. It is not comprehensive coverage for living abroad, routine overseas appointments or an indefinitely long trip. Medigap standardization also differs en Massachusetts, Minnesota and Wisconsin, so confirm the actual policy terms.
Medicare’s explanation of what Medigap covers includes the foreign emergency benefit. ¿Recuerdas that Medigap supplements Medicare Original; it cannot be used to pay deducibles or copayments under Medicare Advantage.
Cruises, evacuation and travel medical insurance
Cruise coverage depends partly on the ship’s location. Medicare may cover otherwise eligible services aboard a ship en a U.S. port or no more than six hours from one when the treating physician is legally permitted to provide medical services aboard the ship. Shipboard care farther away generally falls outside that protection.
Do not assume a cruise line’s medical charge will be processed like a visit to your usual doctor. Keep itemized bills, medical records and proof of payment.
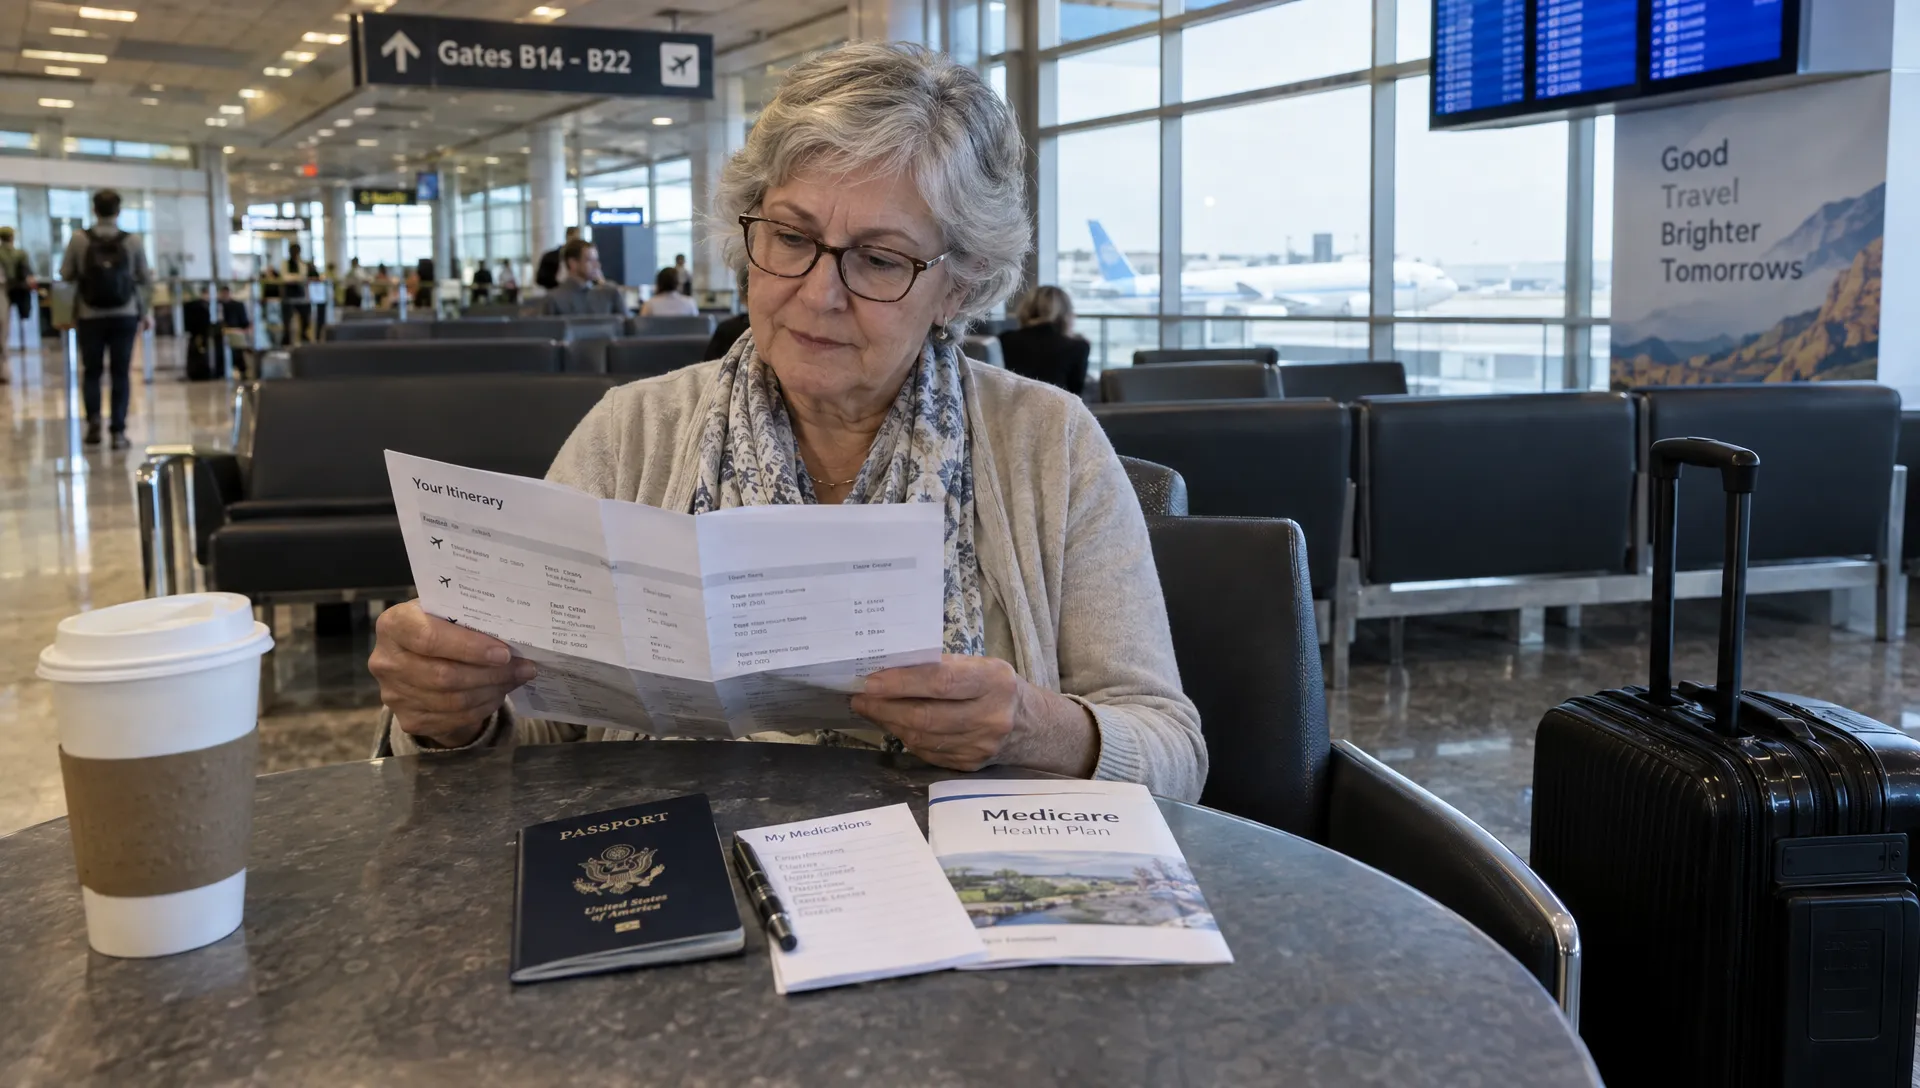
For overseas trips, consider whether separate travel medical insurance is appropriate. Examine preexisting-condition exclusions, medical evacuation, transportation to an appropriate hospital, repatriation and whether the insurer pays providers directly or reimburses you later. Trip-cancellation coverage alone does not establish that your medical expenses are insured.
Compare Total Costs and Prescription Access Away From Home
A low premium does not establish the lowest travel cost
You generally continue paying your Part B premium whether you use Medicare Original or Medicare Advantage. A Medicare Advantage plan advertised with a $0 additional premium is not free medical care.
Medicare Original has no annual out-of-pocket maximum for Part A and Part B services. Medigap can reduce covered cost-sharing, but it adds a separate premium. Stand-alone Part D coverage also typically has its own premium and cost-sharing.
Medicare Advantage has an annual out-of-pocket limit for covered Part A and Part B services. That limit does not mean every travel expense counts toward it. Primas, Part D prescription costs and noncovered services are outside that medical limit, and PPOs may have separate dentro de la red and combined limits.
A useful Medicare Original vs. Medicare Advantage comparison estimates an ordinary travel year and a year with repeated treatment away from home. Include out-of-network charges, supplemental premiums and any separate travel policy, not just the monthly plan premium.
Plan prescription refills before departure
For domestic travel, check whether pharmacies at your destination participate en your Part D or Medicare Advantage drug plan. A chain pharmacy can be dentro de la red without having preferred cost-sharing, so verify the specific location.
Ask whether your plan allows a longer supply, an early refill or a vacation override. Approval is not automatic, especially for controlled medications. Specialty drugs may also involve delivery restrictions, refrigeration or coordination with an approved specialty pharmacy.
Part D generally does not cover prescriptions purchased outside the United States. Buying a medicine overseas and saving the receipt does not guarantee reimbursement.
Before a long trip, confirm your supply with both the pharmacy and insurer. Carry medications en their labeled containers, bring an updated medication list and check destination-country restrictions on the medicines you intend to bring.
Switching Cobertura Requires More Than an Enrollment Date
You can generally join, switch or leave a Medicare Advantage plan during Medicare Open Enrollment, 15 de octubre al 7 de diciembre, with changes effective January 1. People already enrolled en Medicare Advantage can generally make one qualifying change during the Medicare Advantage Período de inscripción abierta, January 1 through March 31.
Períodos de inscripción especial may apply to circumstances such as a qualifying move. A vacation alone does not automatically create one.
The biggest caution when switching from Medicare Advantage to Medicare Original is Medigap eligibility. The right to leave an Advantage plan does not necessarily include a right to buy any Medigap policy without medical underwriting.
Your federal Medigap Período de inscripción abierta generally lasts six months beginning with the first month you are both 65 años o más y esté inscrito en la Parte B. Outside that period, guaranteed-issue protections, trial rights and state rules determine whether an insurer can use underwriting. Coordinate any needed Part D enrollment too.
Before changing Medicare Original vs. Medicare Advantage coverage for travel, confirm the effective dates and whether the supplemental policy you want will actually be available to you.
If you have employer or union retiree coverage, Medicaid or other assistance, check how a change would affect those benefits. People with retiree coverage can review how Group Medicare Advantage works before making an individual enrollment decision that could affect existing coverage or dependents.
A Practical Checklist for Frequent Travelers
Compare planes using the documents for the year en which you will travel. Networks, drug coverage and travel benefits can change annually. A current identification card or last year’s directory is not enough to establish next year’s benefits.
Before enrolling, get answers to these questions:
- Destinations: Does coverage work en every state or country where you expect to spend time?
- Routine care: Can you schedule nonemergency visits at your second home, and which clinicians will treat you?
- Networks and approval: Are the specific doctors, hospitals and treatment facilities covered, and will services require authorization?
- Extended absences: How long can you stay outside the service area without losing plan eligibility?
- Medicamentos recetados: Which destination pharmacies are preferred, and can you obtain enough medication before departure?
- Financial exposure: What are the premiums, out-of-network charges, medical spending limits and overseas benefit caps?
- Claims and emergencies: Who do you contact while away, what records must you keep and will you need to pay upfront?
For Medicare Original vs. Medicare Advantage decisions, ask both the insurer and the provider to confirm access. Request the relevant Evidencia de cobertura section or written benefit explanation, especially for routine out-of-area treatment and foreign emergencies.
You can use Buscador de planes de Medicare to compare local options, then investigate the travel details that matter to your itinerary.
Preguntas frecuentes
Is Medicare Original usually better for frequent travelers? It generally provides broader access to Medicare-accepting providers across the U.S., which can help people who need routine care en multiple states. The financial comparison still depends on supplemental coverage, premiums and expected treatment. It does not provide broad international .
Can I use a Medicare Advantage PPO anywhere en the country? A PPO generally offers covered out-of-network care, but that does not guarantee every provider will treat you or that costs will match dentro de la red rates. Confirm the service, provider participation, authorization requirements and cost-sharing before scheduling nonemergency treatment.
Will Medicare cover an emergency while I am overseas? Medicare Original usually will not, except en limited circumstances. Certain Medigap policies and planes Medicare Advantage offer foreign emergency benefits, but limits apply. Check whether separate travel medical and evacuation coverage is appropriate.
Does a nationwide insurer mean I have nationwide routine coverage? No. The company’s national presence does not determine your individual plan’s network. Look for explicit out-of-area routine-care benefits rather than relying on the insurer’s name.
Can I return to Medicare Original before a long trip? You can make changes during an applicable enrollment period, but travel plans alone do not guarantee a Período Especial de Inscripción. Confirm whether you can obtain Medigap, arrange prescription coverage and check all effective dates before canceling existing .
Compare Cobertura Around Your Actual Travel Plans
Bring your home Código postal, travel destinations, expected time away, medications and provider list to a coverage review. Those details make the comparison more useful than choosing by premium or extra benefits alone.
Los asesores con licencia de Seguros2All offer free, no-commitment Medicare plan comparisons, bilingual guidance and enrollment application support. Ask specifically about routine care away from home, extended-stay rules and overseas benefit limits before choosing a plan.